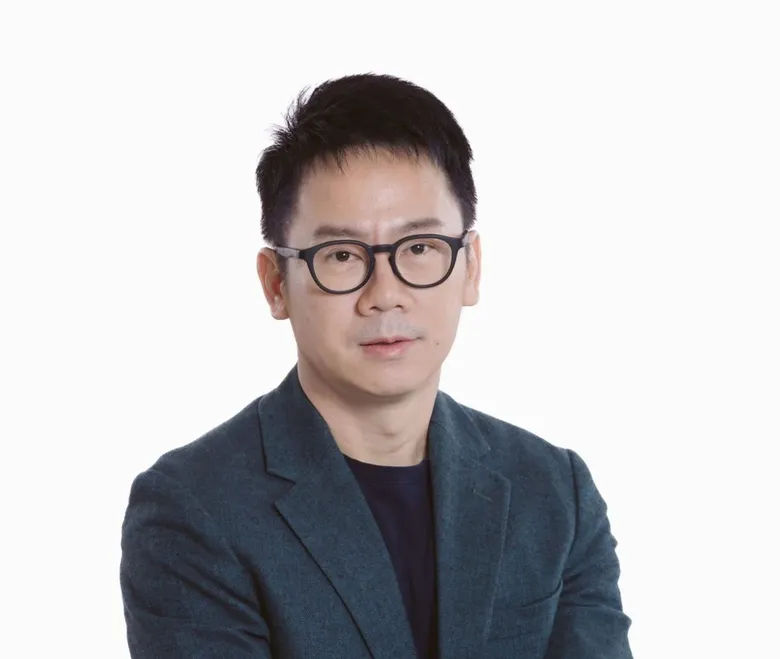
Niphan Srisukhumbowornchai, Tax and Legal Leader at PwC Thailand, spoke at the event 'Maximising Shareholder Value: The next journey of tax and value creation'. The seminar is part of PwC Thailand's 2026 Tax Symposium.
He said that the question for business leaders is no longer whether they can keep pace with regulatory change. It's whether they can anticipate change and respond to it proactively and strategically.
"The tax landscape is changing rapidly, and the authorities can now analyse business data at a scale and speed that was not possible a few years ago. Tax and customs issues that once went unnoticed are now far easier to detect," Niphan said.
"Businesses that respond proactively, with strong data, clear governance and well-documented positions, will not only reduce their risk. They'll also be better placed to protect margins, support transactions and create long-term business growth," he said.
A broad wave of regulatory change
Niphan noted that regulatory change in Thailand is no longer confined to tax. As the country moves closer to Organisation for Economic Co-operation and Development (OECD) standards, the authorities are tightening rules across tax and corporate law to broaden the revenue base and close gaps that have long been left untouched. Business structures are also coming under closer scrutiny. The Department of Business Development is clamping down on nominee shareholding arrangements and tightening oversight of foreign control of businesses through Thai companies.
At the same time, an increasingly volatile global trade environment is adding cost and compliance pressure to businesses' supply chains. Examples include shifting US tariff policy and Thailand's new export and re-export licensing requirements for Category 0 nuclear-related dual-use items--goods with both civilian and military applications.
"Not every change will affect every business equally. Understanding which developments matter most to your business, and acting on them early, is what separates managing risk from identifying opportunity," Niphan said.
Data-driven audits raise the stakes
Niphan pointed to the recent IMF-World Bank Group Annual Meetings 2026, hosted in Bangkok from 12 to 18 October 2026, as a clear signal of where Thailand's tax policy is heading.
At the meetings, the Ministry of Finance showcased how digital technology is linking revenue collection with public spending. It also confirmed plans to use technology to bring more foreign businesses and digital platforms into the tax net. Thailand held bilateral discussions with more than 50 countries on tax and investment cooperation, and the Ministry indicated that big data and AI will play a growing role in managing public finances.
"Thailand's tax reforms are now firmly part of a global conversation. For businesses, that means the direction is clear, and the pace of change is unlikely to slow," Niphan said.
Visibility is also extending beyond Thailand's borders. Tax authorities already exchange financial account information automatically under the Common Reporting Standard (CRS). The Crypto-Asset Reporting Framework (CARF) is intended to extend automatic exchange to crypto-asset transactions as jurisdictions implement it. Together, these developments are increasing transparency around offshore income, assets and transactions, making strong tax governance a strategic business priority rather than a back-office function.
Making tax part of the investment decision
As more Thai companies look abroad for growth, Niphan noted that tax is moving from a post-deal consideration to a core part of investment decisions. For multinational groups within its scope, the global minimum tax is narrowing the benefits of low-tax jurisdictions, while tax authorities are increasingly coordinating across borders. Together, these changes mean that structures that worked in the past may no longer deliver the returns businesses expect.
"Many of the tax costs in an overseas investment are set the moment a deal is structured, yet they often only surface years later. Bringing tax into the conversation early, from deal planning through to how the business operates after acquisition, is one of the most effective ways to protect returns," he said.
Preparing for the next phase of digital tax
Niphan said the next phase of change will be driven by technology. The Revenue Department's announced AI development plans focus on improving tax administration, speeding up analysis and audits, and analysing filing and payment behaviour to tailor taxpayer services.
These plans signal a more digital, data-driven approach to tax administration. As digital capabilities develop, businesses will need accurate data and well-documented tax positions to support compliance.
Niphan stressed that companies will need to invest in their own digital capabilities to keep pace with an increasingly digital, data-driven tax administration. This will include integrated systems, clean and consistent data, and greater use of automation and AI within the tax function. For businesses, this means tax data can no longer sit in separate systems or be pulled together only at year-end.
"Thailand's tax system will continue to evolve alongside international standards. That journey is already underway, and the businesses that move with it, rather than react to it, will be the ones that achieve sustainable growth," he concluded.